
TAX APPEAL PROPERTY TYPES
Car Dealership Property Tax Appeal Consulting in New Jersey
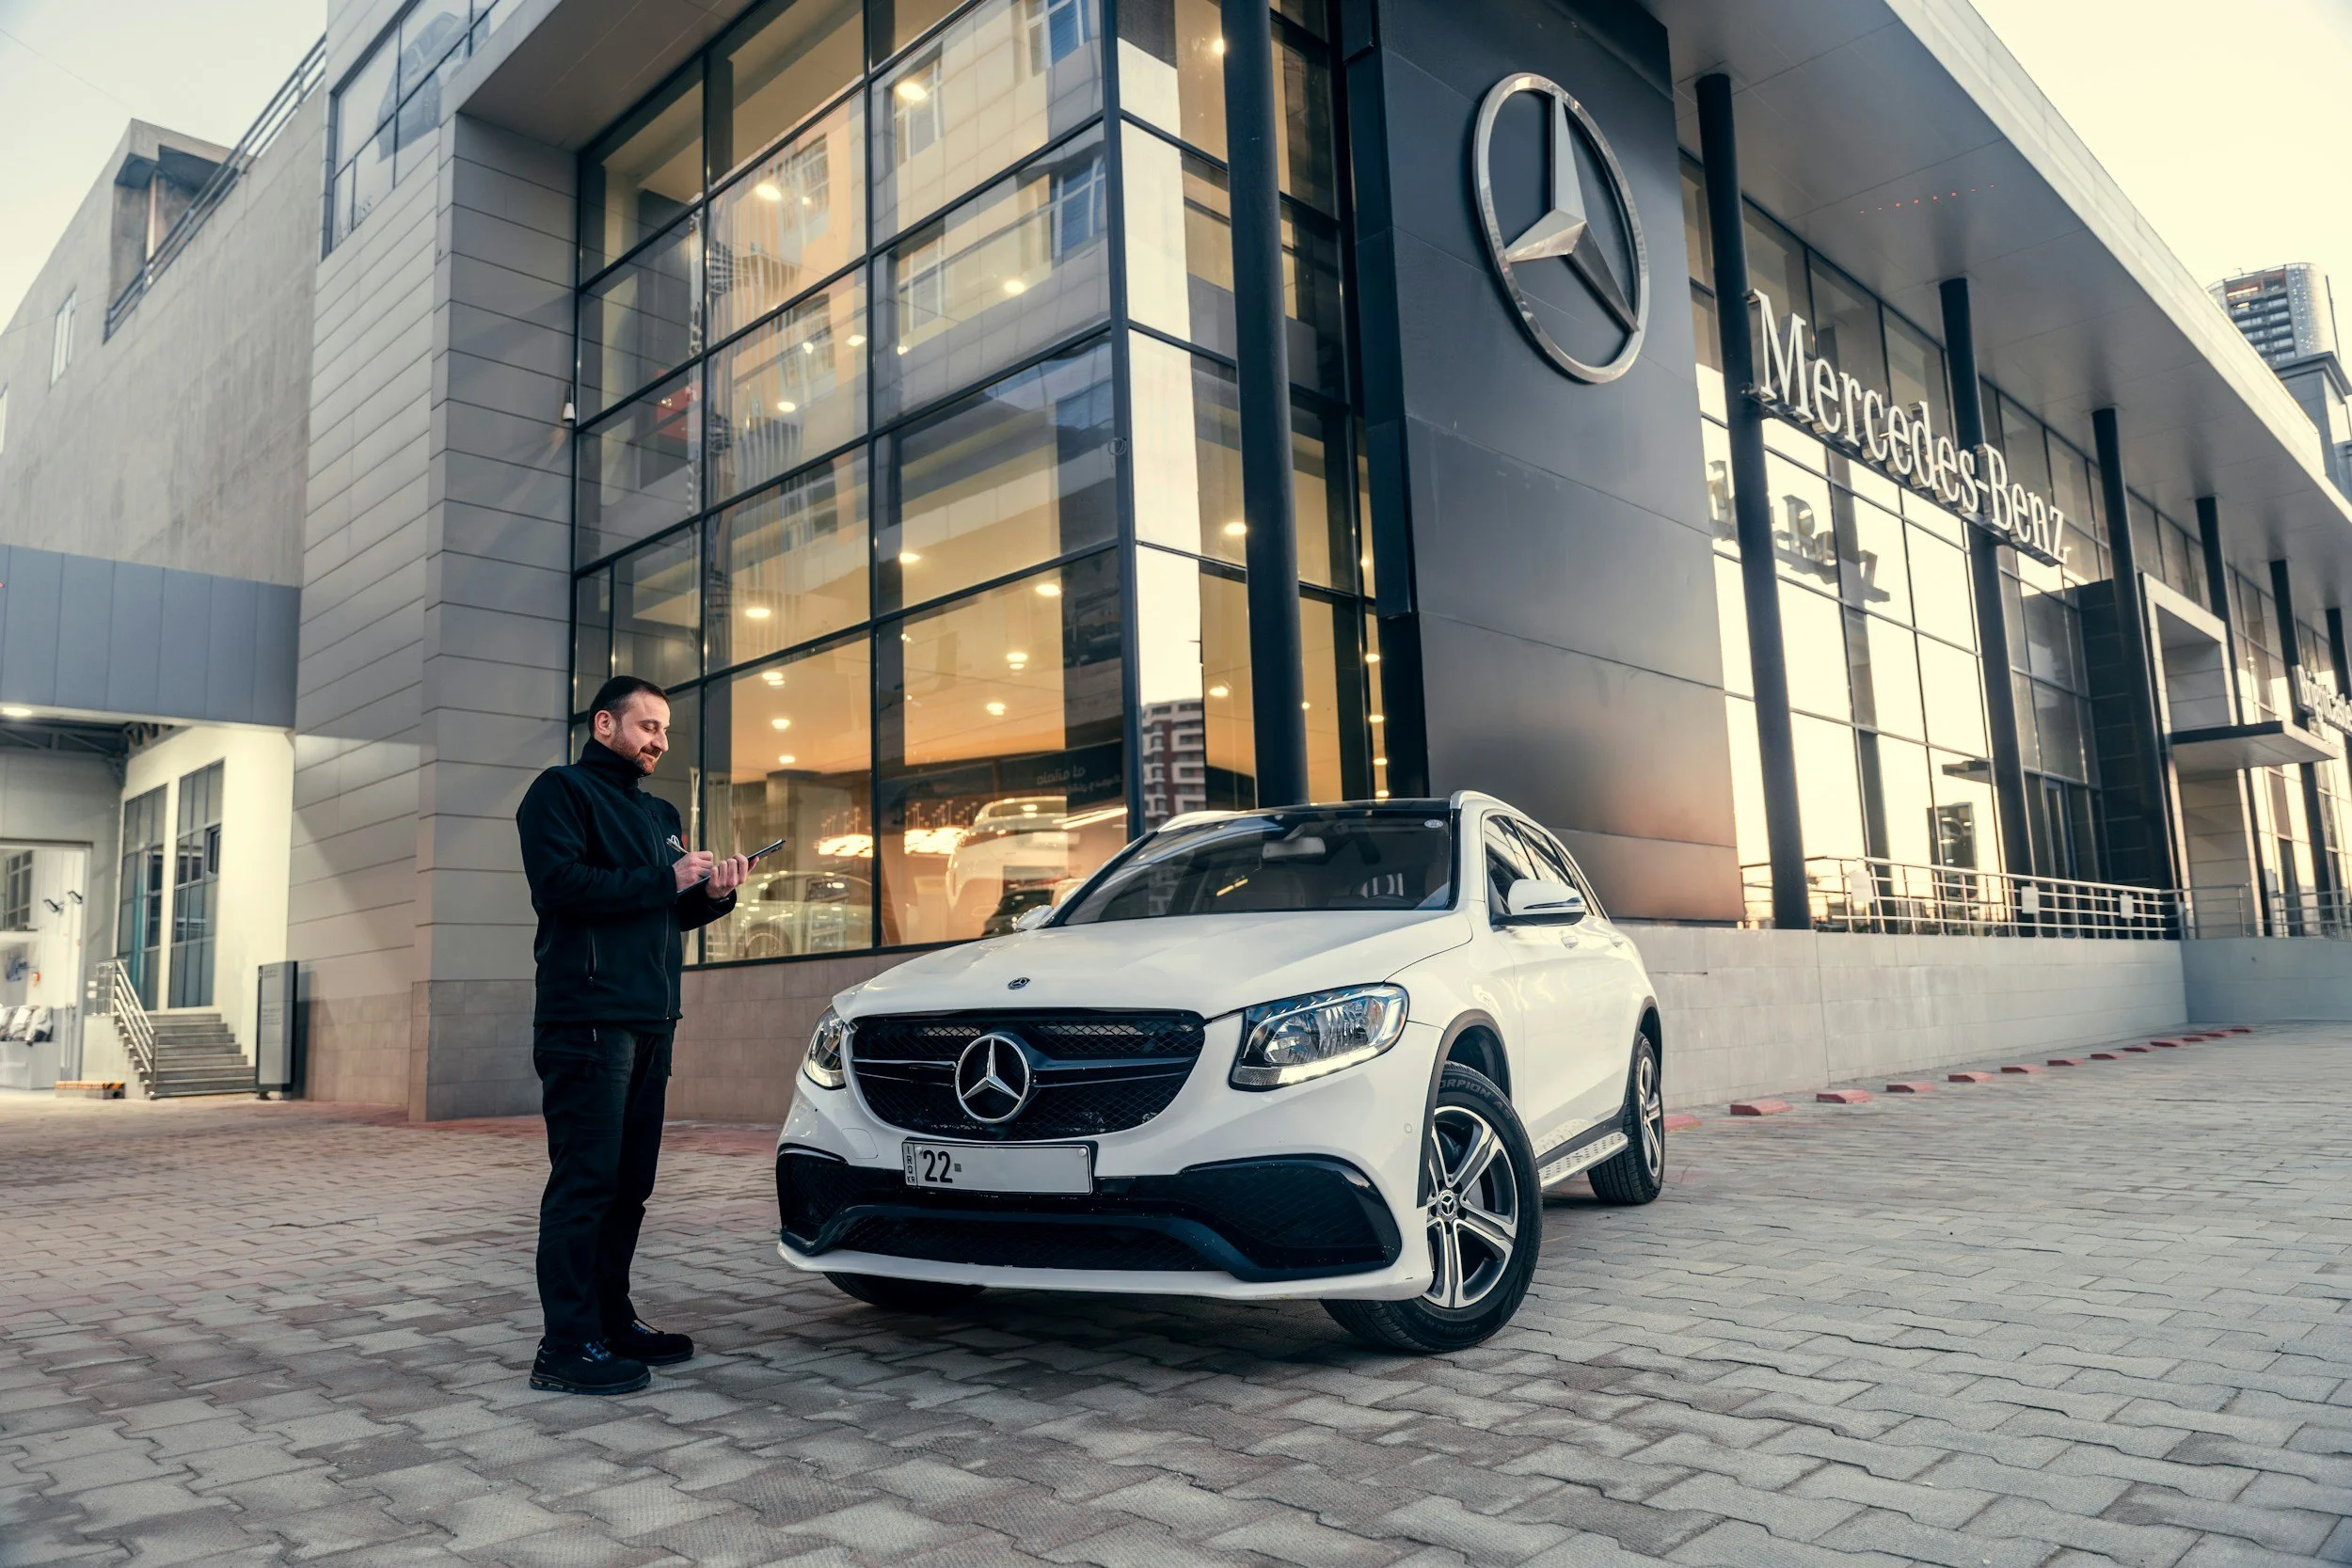
Car dealerships are specialized properties where land area, frontage, visibility, access, vehicle storage, showroom and service capacity, site configuration, zoning, and the usefulness of specialized improvements can affect real estate value.
Who this is for
This page is for New Jersey owners, investors, and property managers responsible for:
New- and used-vehicle dealership owners
Owners of showroom and service-center properties
Dealership operators who own the real estate
Investors and landlords who lease dealership sites
What affects a car dealership assessment
NJPTC reviews the physical real estate and its usefulness to the market. A property with strong frontage and vehicle-storage capacity may differ from a site with access, layout, parking, or zoning limitations, even when the building area appears similar.
The dealership business, inventory, franchise, and other non-real-estate assets should not automatically be treated as taxable real estate value. Specialized improvements are considered according to how useful they would be to another market participant.
Common assessment issues to review
Land value or excess-land assumptions that do not reflect the site
Showroom, service, office, and vehicle-storage areas treated as one undifferentiated use
Access, layout, parking, zoning, or market-decline issues not reflected
Business, inventory, franchise, or other non-real-estate value included improperly
How this property may be analyzed
Comparable dealership or related-property sales
Market-rent and income analysis when the property is leased
Land, building, site-utility, and specialized-improvement analysis
Information NJPTC may review
Current assessment, tax bill, and property record
Land area, frontage, visibility, and access
Showroom, office, and service-bay space
Parking and vehicle-storage capacity
Site configuration and zoning
Condition and specialized improvements
Comparable property sales and market rents
Business, inventory, franchise, and other non-real-estate components
Learn more about commercial property tax appeal consulting in New Jersey and what the No-Fee Review includes.
Frequently asked questions
Does the dealership business count as real estate value?
Business, inventory, franchise, and other non-real-estate assets should not automatically be included in taxable real estate value. The review focuses on the real property and market evidence.
Can specialized improvements affect the assessment?
Yes, but cost does not automatically equal market value. NJPTC considers whether the improvement contributes to the real estate and would be useful to another market participant.
What should a dealership owner provide?
Start with the assessment, tax bill, property record, land and building details, photographs, and any NJPTC letter. Purchase documents, leases, income information, appraisals, or site plans may also help.
Request a No-Fee Review of Your Car Dealership
Send the property address or block and lot, current assessment, annual tax bill, and any assessment notice or NJPTC letter you received. NJPTC will review the available information and let you know whether additional records are needed. There is no fee for the initial review and no obligation to proceed.